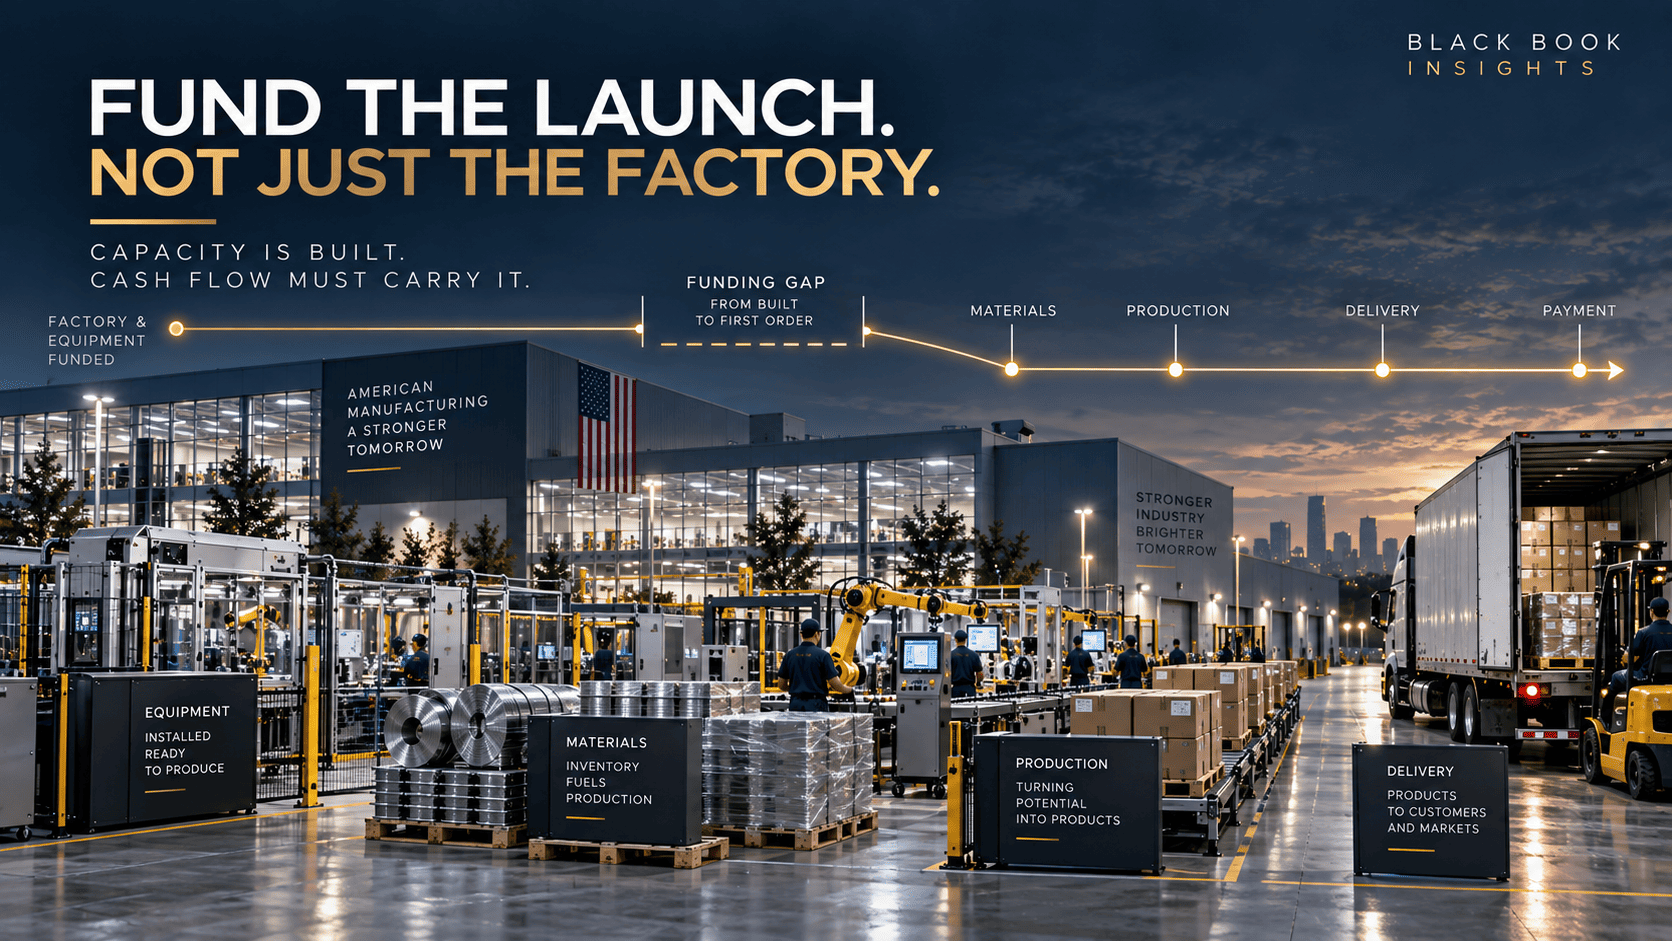
Reshoring needs financing for two different achievements: establishing production capacity and carrying the business through the period before that capacity generates cash.
Consider a domestic manufacturer preparing to take over production previously performed overseas.
The equipment financing is approved. The facility is available. A customer wants the product.
Now materials must be purchased, workers trained, trial production completed, and inventory carried. Customer acceptance and payment are still ahead.
The business has a funded factory. It may not yet have a funded launch.
That is the distinction Black Book recommends putting at the center of September’s reshoring financing reviews.
The financing menu has changed
An SBA policy change effective July 4, 2026, expanded the ability of qualified borrowers to combine financing across the 7(a) and 504 programs. SBA describes a structure in which qualified borrowers obtaining a 7(a) loan first may access up to $5 million through that program and up to $5 million through the 504 program, for a combined $10 million.
The change matters because the programs can serve different needs. SBA describes 504 financing as supporting major fixed assets, while 7(a) financing can support working capital and other eligible business purposes. The combined-financing change does not turn every individual loan into a $10 million facility or eliminate underwriting and eligibility requirements.
Manufacturers also have the Manufacturers’ Access to Revolving Credit program, known as MARC. SBA designed it to support short-term working-capital needs, including inventory and new projects, with structures that may take the form of revolving credit or a term loan.
The opportunity is to match financing to the operating need rather than force the entire reshoring project into one loan structure.
Separate three different cash requirements
Black Book recommends treating the financing plan as three connected commitments.
The first is the production asset: the building, equipment, installation, and other long-lived capability.
The second is the launch: the cash required to prepare the operation, establish the process, train personnel, complete qualification activities, and reach the planned production condition.
The third is ongoing working capital: the money tied up between purchasing inputs and collecting from customers.
These requirements should be modeled together, but they should not be confused.
A long-term equipment facility does not, by itself, demonstrate that sufficient cash will be available for the launch. Likewise, a working-capital line should not be treated as unlimited protection against a production schedule that repeatedly slips.
The planning question is not simply how much financing is available. It is when money can be drawn, what it can pay for, and when repayment or other obligations begin.
Make the customer contract part of the financing discussion
A reshoring team should bring commercial terms into the cash model before accepting a major production transfer.
When can the manufacturer invoice? What must happen before the customer accepts the product? Who pays for dedicated tooling? What happens to specialized inventory if the forecast changes? Are minimum purchases binding, or merely anticipated?
Black Book recommends resolving these questions jointly across finance, sales, operations, and the customer relationship team.
Where commercially appropriate, the parties can evaluate deposits, milestone payments, tooling contributions, inventory arrangements, or commitments covering dedicated capacity.
The objective is not to make the customer finance the entire project. It is to allocate launch risk consciously rather than allow it to accumulate invisibly on the smaller manufacturer’s balance sheet.
September is the time to reprice the plan
SBA has published fiscal year 2027 fee notices for both the 7(a) and 504 programs, effective October 1, 2026. Manufacturers pursuing financing across the fiscal-year boundary should have lenders confirm which fee schedule and exceptions apply to the anticipated approval and financing structure.
More broadly, a reshoring proposal approved earlier in the year deserves an updated cash review before the next operating phase.
Black Book recommends showing the projected lowest cash balance under the base case and under a delayed-launch case. The delayed case should examine slower qualification, later customer acceptance, additional inventory, and other material project-specific exposures.
The exercise should identify an actual funding response. “Management will monitor liquidity” is not a financing commitment.
A smaller, phased transfer may be preferable to a larger launch whose working-capital requirement has not been secured.
Black Book’s position: reshoring is not fully financed when the equipment can be purchased. It is financed when the manufacturer has a credible path through startup, delivery, acceptance, and collection.
The factory creates the capability. The cash plan keeps it operating long enough to become a business.